Home Financing Options for Buying a Home
Understanding Your Home Financing Options
The right option depends on factors such as your credit profile, income, available savings, property price, intended occupancy, and how long you expect to own the home.
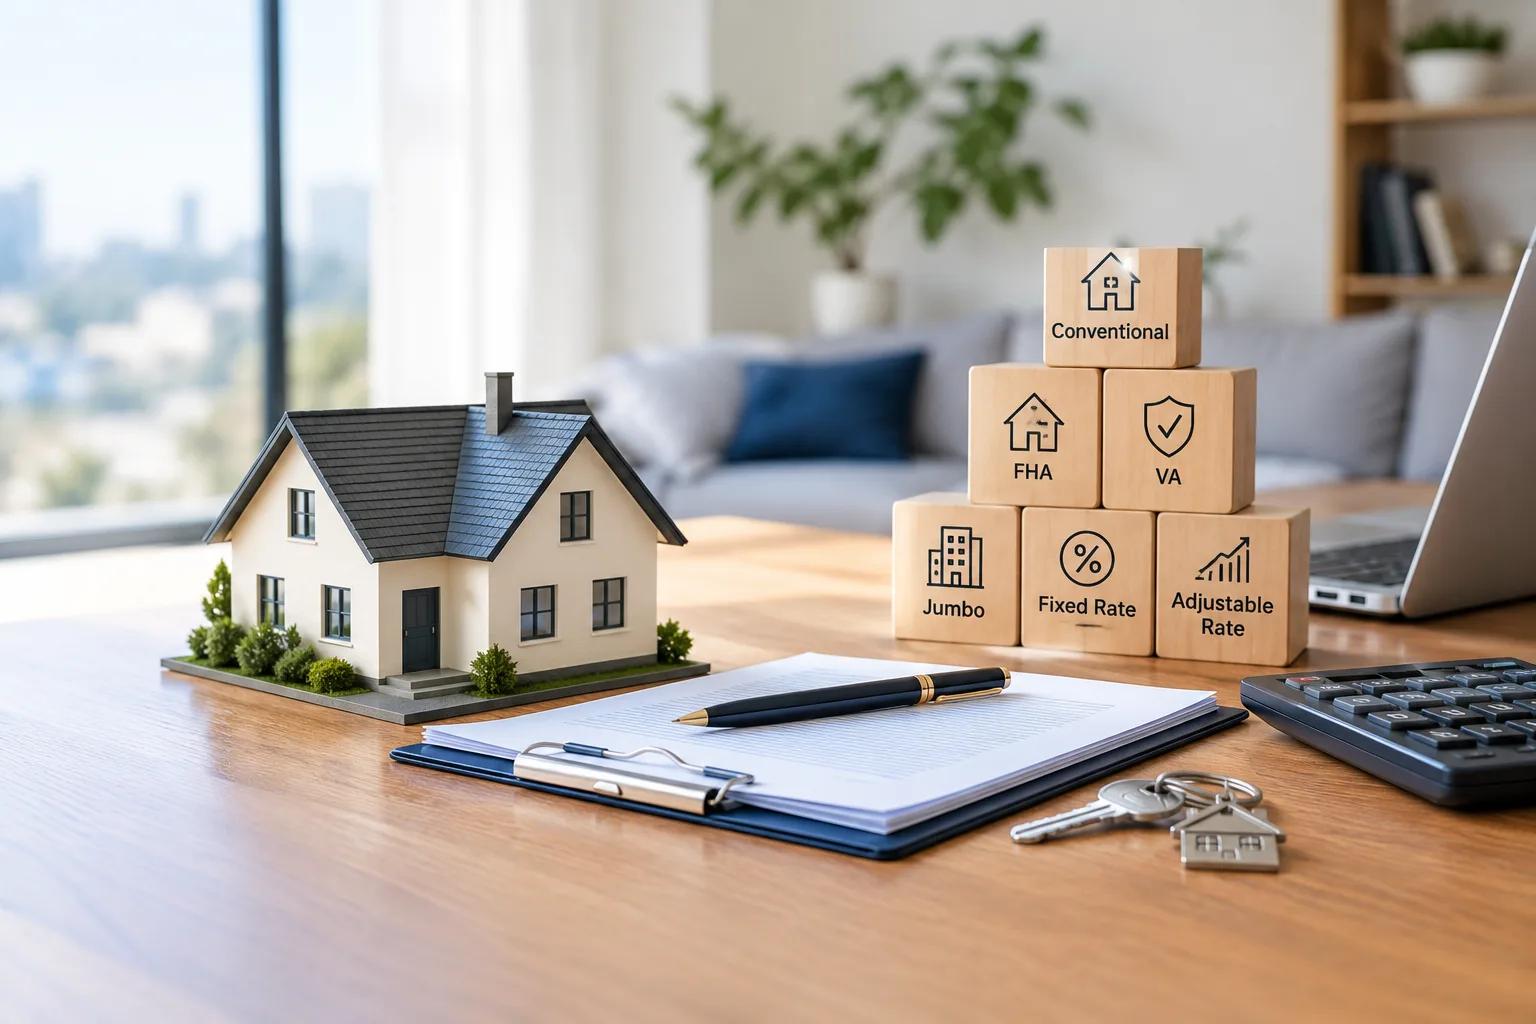
Common home financing options include conventional mortgages, FHA loans, VA loans, jumbo loans, fixed rate mortgages, adjustable rate mortgages, and certain alternative financing arrangements.
Conventional Mortgage Financing
A conventional mortgage may suit buyers who meet the lender’s credit, income, debt, and down payment requirements. Some conventional loan programs allow eligible buyers to purchase a home with a relatively small down payment.
Balloon Mortgages
These loans can create significant repayment risk if the borrower cannot pay the balance, refinance, or sell the property when required. Buyers should review the repayment terms carefully and avoid assuming that refinancing will always be available.
Fixed Rate Mortgages
Fixed rate financing may be suitable for buyers who value payment stability and expect to keep their mortgage for an extended period.
Two Step Mortgages
Before choosing this type of financing, confirm when the adjustment occurs, how the new rate is determined, and whether payment limits apply.
Adjustable Rate Mortgages
An ARM may appeal to buyers who expect to move or refinance before the first adjustment. However, future adjustments can increase monthly payments, so buyers should understand the adjustment schedule, rate limits, and potential payment changes before proceeding.
Jumbo Loans for Higher Value Homes
Jumbo mortgage requirements vary by lender and may include stronger credit, additional financial reserves, detailed income documentation, and a larger down payment. Interest rates and fees depend on the borrower’s profile, property, loan amount, and current market conditions.
Federal Government Mortgage Programs
FHA Loans
FHA eligibility depends on the borrower’s financial profile, property requirements, applicable loan limits, and program rules. FHA loans also have mortgage insurance requirements that buyers should include when comparing the overall cost of financing.
VA Loans
Eligibility, the Certificate of Eligibility, funding fee requirements, and property standards should be reviewed before applying. Buyers can compare VA financing with other suitable mortgage options to understand the potential benefits for their situation.
Alternative Home Financing Options
Alternative arrangements require careful review because the payment structure, ownership rights, and risks can differ from a standard mortgage.
Home Equity and Bridge Financing
These options depend on available equity, lender requirements, the existing mortgage, and the borrower’s ability to manage overlapping costs. If the current home takes longer than expected to sell, the borrower may face additional financial pressure.
Second Mortgages
A second mortgage adds another repayment obligation and may increase the borrower’s overall financial risk. Buyers should review the interest rate, fees, repayment schedule, and relationship between the first and second loans.
Seller Financing and Installment Contracts
An installment contract may allow the buyer to make payments over time under specified terms. The agreement should clearly address the purchase price, interest rate, payment schedule, default consequences, and when legal title transfers.
Because the legal and financial consequences can be significant, buyers should consult qualified real estate and legal professionals before entering this type of arrangement.
Lease Purchase and Lease Option Agreements
These arrangements are not the same as mortgage approval. Buyers should obtain independent legal advice and confirm how the agreement affects their ability to purchase the property later.
Questions to Ask Before Choosing a Mortgage
How to Choose the Right Home Financing Option
Choosing a mortgage starts with understanding your purchase budget and financial priorities.
First, estimate how much you can comfortably contribute toward the down payment and closing costs. Next, review your income, credit history, existing debts, and available savings to understand which loan programs may fit your circumstances.
Compare eligible conventional, FHA, VA, and jumbo options where appropriate. Review the interest rate, loan term, mortgage insurance, lender fees, and expected monthly payment rather than focusing on one number alone.
Finally, confirm that the financing matches your intended property and long term plans. A mortgage professional can help you compare available options, understand lender requirements, and identify the next steps toward preapproval.
Home Financing Options in Los Angeles and California
Local property prices can make loan size, down payment planning, and closing costs especially important. Buyers should also account for property taxes, homeowners insurance, homeowners association fees where applicable, and other costs associated with owning a home.
Crestico helps buyers explore home financing options and connect their real estate goals with suitable mortgage guidance. Whether you are buying your first home or considering a higher value property, comparing your options can help you approach the purchase with greater confidence.